
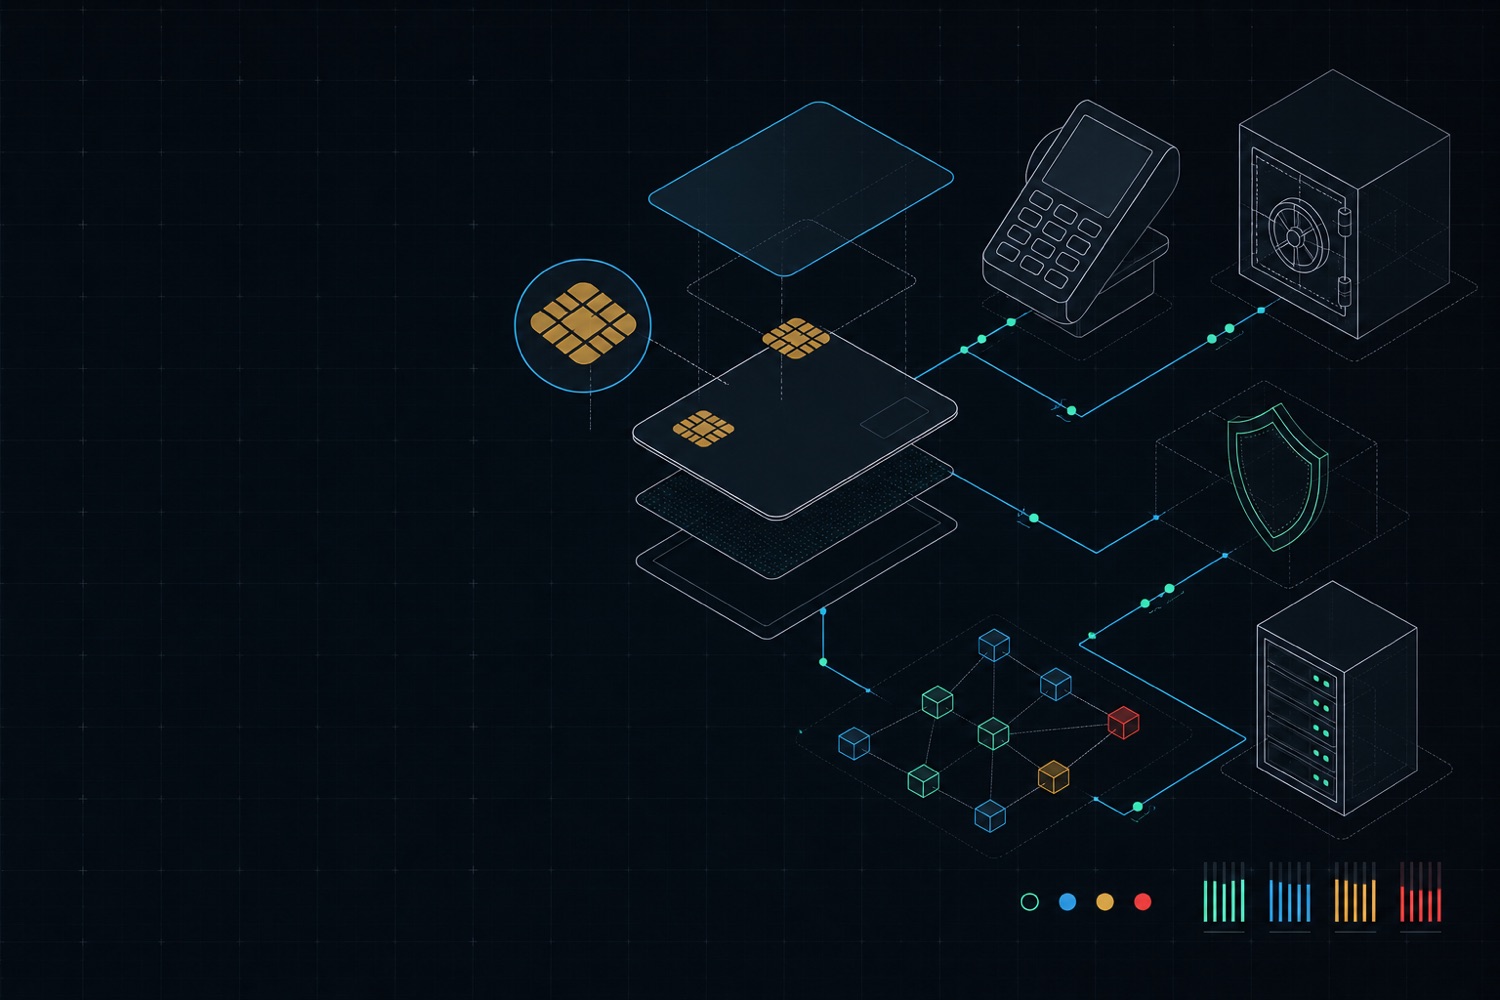
Do casinos take credit cards in Canada? Yes — almost all of them, and the deposit usually goes through on the first try. What surprises people is everything that happens after: a C$100 deposit that shows up on the statement as a cash advance with a fee and same-day interest, a card that works on Tuesday and is refused on Friday, and a payout that comes back by Interac instead of to the card it came from.
This page takes the credit card path apart step by step for Canadian players. It covers Visa and Mastercard acceptance, what merchant category code 7995 does to your transaction, how Canadian issuers differ, what to do with a declined deposit, whether a casino can refund winnings to a card, and which alternatives cost less. The eighteen casinos below were checked from a Canadian connection with real card deposits.
Best credit card casinos in Canada — 2026
Scored on card acceptance rate, whether the site is regulated in Ontario, whether Amex works, the minimum deposit, and whether winnings can go back to the card rather than to a wallet.
-
9.8
BetMGM Ontario
iGaming Ontario / AGCO · Visa · Mastercard Regulated ONAmexC$10 min
100% up to C$1,000 + C$50 bonuswagering 15× · card deposit qualifiesVisit casinopayout 24–48 h -
9.7
bet365 Casino
iGaming Ontario / AGCO · Visa · Mastercard Regulated ONAmexCard payouts
100% up to C$500 on first depositwagering 20× · min C$10Visit casinopayout 1–5 days -
9.5
NorthStar Bets
iGaming Ontario / AGCO · Canadian operator Regulated ONVisaC$10 min
Up to C$500 in casino bonuseswagering 25× · Interac payoutsVisit casinopayout 24–72 h -
9.4
LeoVegas
MGA · Ontario site available Regulated ONAmexCard payouts
100% up to C$1,000 + 200 free spinswagering 35× · min C$10Visit casinopayout 1–5 days -
9.3
Betway
MGA · Ontario site available Regulated ONAmexCard payouts
100% up to C$1,000 on first depositwagering 50× · min C$10Visit casinopayout 1–5 days -
9.2
Casino Days
Curaçao · Visa · Mastercard · Interac CADC$10 min
100% up to C$1,000 + 100 free spinswagering 35× · e-wallets also fineVisit casinopayout 24–48 h -
9.1
Lucky Days
MGA · Visa · Mastercard CADCard payouts
100% up to C$1,000 + 100 free spinswagering 35× · min C$20Visit casinopayout 1–5 days -
9.0
Rizk
MGA · Visa · Mastercard · Interac CADC$10 min
100% up to C$500 + 50 free spinswagering 35× · low max-bet ruleVisit casinopayout 24–72 h -
8.9
Spin Casino
MGA · long-standing Canadian brand CADAmexCard payouts
Up to C$1,000 across three depositswagering 70× · min C$10Visit casinopayout 24–48 h -
8.8
LuckLand
MGA · cards and prepaid CADC$10 min
100% up to C$500 + 100 free spinswagering 35× · prepaid acceptedVisit casinopayout 24–48 h -
8.7
22Bet
Curaçao · casino and sportsbook CADC$10 min
100% up to C$450 on first depositwagering 50× · many card BINs acceptedVisit casinopayout 15 min – 24 h -
8.6
National Casino
Curaçao · Visa · Mastercard CADInterac
100% up to C$500 + 100 free spinswagering 40× · min C$30Visit casinopayout 12–48 h -
8.5
Vulkan Vegas
Curaçao · card and wallet mix CADPrepaid
100% up to C$300 + 25 free spinswagering 40× · min C$20Visit casinopayout 12–24 h -
8.4
Mr Bet
Curaçao · live dealer heavy CADMastercard
100% up to C$400 + 50 free spinswagering 30× · min C$20Visit casinopayout 24–48 h -
8.4
FastPay Casino
Curaçao · fastest payout desk on this list CADCard payouts
100% up to C$300 + 100 free spinswagering 40× · min C$20Visit casinopayout 10 min – 1 h -
8.3
BitStarz
Curaçao · card in, crypto out CADCrypto
100% up to C$500 + 180 free spinswagering 40× · min C$20Visit casinopayout under 10 min -
8.2
Cobra Casino
Curaçao · weekly reloads CADPrepaid
100% up to C$500 + 250 free spinswagering 40× · min C$20Visit casinopayout 12–24 h -
8.1
PlayZilla
Curaçao · large slot catalogue CADInterac
100% up to C$500 + 200 free spinswagering 40× · min C$20Visit casinopayout 12–24 h
Advertising disclosure. The buttons here are commercial links and we may be paid if you open an account. Order follows the scoring described above and is not for sale. Bonus figures are quoted in Canadian dollars as published for Canadian players; card acceptance and promotions change constantly, so verify in the cashier before depositing. Regulated Ontario products are open to Ontario residents only. 19+ in most provinces, 18+ in Alberta, Manitoba and Quebec. Free confidential help: ConnexOntario 1-866-531-2600.
What happens when you deposit with a credit card
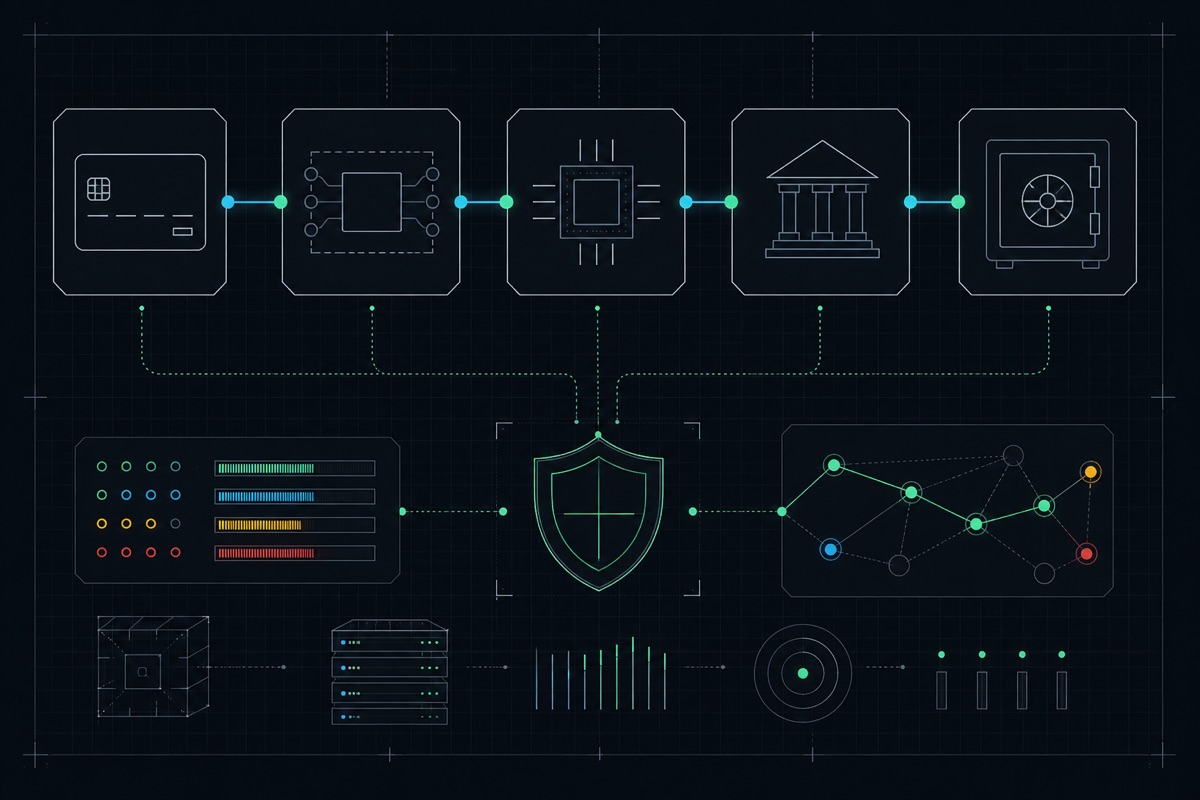
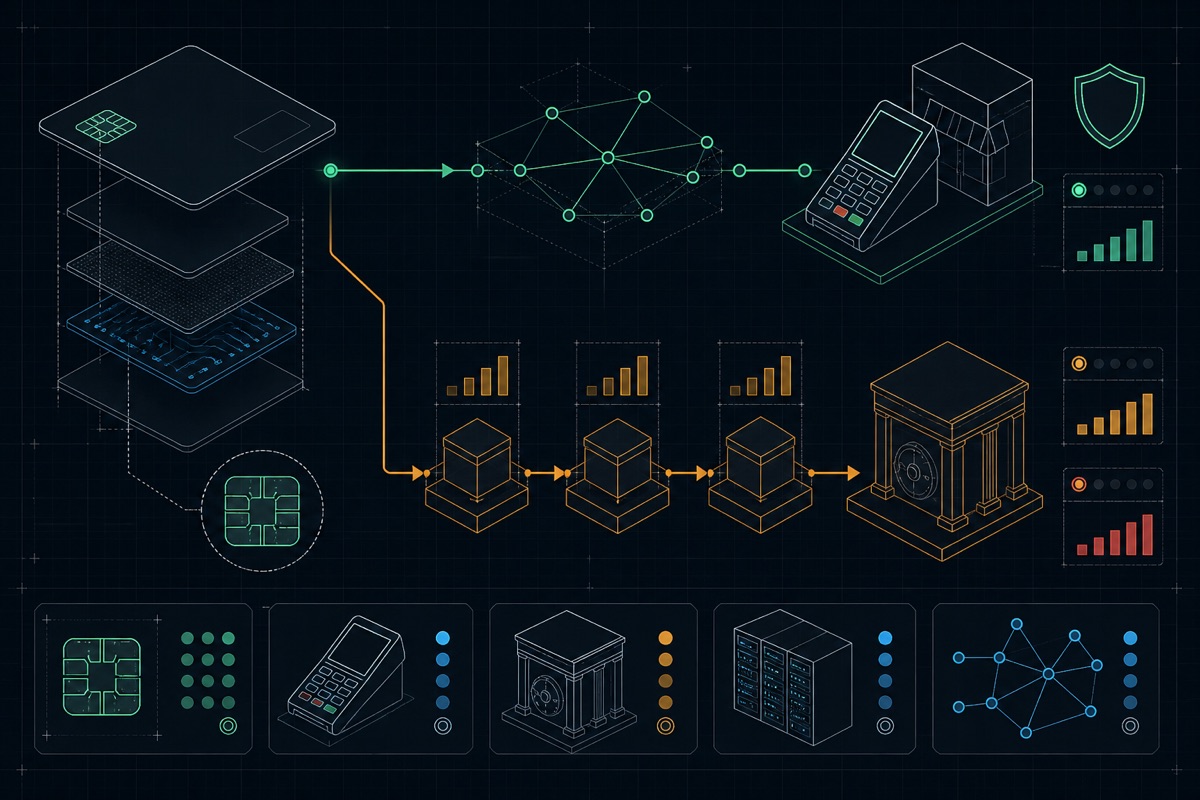
A casino deposit is an ordinary card purchase with one unusual field. The payment gateway tags the merchant with category code 7995 — betting and wagering — and that tag travels with the authorisation request all the way to your issuing bank. Everything that follows is decided by what your issuer does with those four digits.
- The cashier collects the card details and hands them to a payment gateway; the casino itself never stores the number.
- The gateway routes the request through the acquiring bank to Visa or Mastercard with the 7995 tag attached.
- Your issuer approves, declines, or approves it as a cash advance — a decision made in about a second, using rules you cannot see.
- On approval the casino credits your balance instantly and the charge posts to your statement within a day or two.
The cash-advance trap
This is the single most expensive thing about credit card gambling in Canada, and it is invisible at the moment of deposit. Many Canadian issuers treat a gambling charge as a cash advance rather than a purchase. Three things then change at once: a flat fee of roughly C$3 to C$5 is added, interest starts accruing that same day with no grace period, and the cash-advance interest rate — often 21% to 23% — is higher than your purchase rate.
A C$200 deposit carried for a month can therefore cost around C$8 before you have placed a single bet. Paying the card off in full at the end of the month does not undo it, because the interest began the moment the charge posted.
- Check your statement after the first deposit and look at how the transaction is classified, not just the amount.
- A debit card, Interac transfer or prepaid card avoids the classification entirely.
- If the charge did post as a cash advance, pay it down immediately rather than at the statement date.
Never treat a credit card as a bankroll. Gambling with borrowed money at 22% is the mechanism behind most of the debt stories in this sector. If the money is not already yours, do not deposit it.
Which Canadian banks allow online gambling?
There is no public register of this, policies differ between a bank's credit and debit products, and they change without notice. What follows is the shape of the market as our test deposits found it — treat it as a starting point and confirm with your own issuer, since a single phone call gives you a definitive answer for your account.
| Issuer | Credit card deposits | Coded as cash advance? | Notes |
|---|---|---|---|
| RBC | Often approved | Frequently | Watch the statement classification closely |
| TD | Often approved | Frequently | Debit via Interac is the cleaner route |
| Scotiabank | Mixed | Sometimes | Varies by card product |
| BMO | Mixed | Sometimes | Higher decline rate on larger amounts |
| CIBC | Mixed | Sometimes | Regulated Ontario sites fare better |
| Desjardins | Mixed | Sometimes | Common Quebec choice; call to confirm |
| Tangerine | Often approved | Sometimes | Money-Back card is a frequent CA pick |
| KOHO | Usually works | No — prepaid | Reloadable prepaid Mastercard; no credit exposure |
| Neo Financial | Mixed | Sometimes | Depends on the card tier |
Two details are worth knowing before you phone your bank. First, the policy on a chequing account is often different from the policy on the credit card attached to it, so ask about both. Second, several Canadian issuers will apply a permanent gambling block to an account at the cardholder's request and refuse to lift it for a set cooling-off period — a tool worth remembering if the problem you are solving is not really a declined deposit.
The pattern is consistent: the more a product looks like a prepaid or debit card, the more likely a gambling transaction is to clear and the less it costs. That is why KOHO turns up so often in Canadian casino discussions — it is a reloadable prepaid Mastercard, so there is no cash advance to trigger and no credit line to protect.
Why the deposit was declined
A declined card at a casino is almost never the casino's doing. The refusal comes from the issuer, and the error text you see in the cashier is a generic translation of a code the casino never sees in detail. These are the causes in order of how often we hit them.
- Issuer policy on 7995. The bank blocks gambling merchants outright on that product. No retry will fix it.
- Cash-advance limit reached. Your card has a separate, much smaller cash-advance ceiling than its credit limit.
- Cross-border flag. The casino's acquirer is offshore and the charge is in euros; a CAD-billing casino often clears where a euro one does not.
- Velocity check. Three or four attempts in a row look like card testing and freeze the card for the day.
- AVS mismatch. The billing address on the casino account does not match the one your issuer has.
The fastest fix is usually a smaller amount on a debit or prepaid card at a casino that bills in Canadian dollars. If that still fails, the block is at the account level and your issuer has to lift it.
Visa, Mastercard and American Express compared
All eighteen casinos on this page accept both Visa and Mastercard; Amex is the one that varies. In practice the differences that matter to a Canadian player are acceptance breadth, payout support and how your particular issuer codes the charge.
| Network | Deposit acceptance | Withdrawals | Notes |
|---|---|---|---|
| Visa | All 18 sites | Supported at 6 | Visa Debit clears more often than Visa credit |
| Mastercard | All 18 sites | Rare | Network rules restrict gambling payouts in several markets |
| American Express | 5 sites | No | Mostly the regulated Ontario operators |
| Prepaid Mastercard (KOHO and similar) | Most sites | No | No cash advance, hard spending cap |
If you want winnings to return to a card, Visa is the network to use and the casino has to support original credit transactions — six of the eighteen do. Everyone else pays by Interac, e-wallet or bank transfer, which is often faster anyway.
Withdrawing to a credit card
A card payout is not the mirror image of a deposit. Where it is supported, the casino sends either a refund against your original purchase or an original credit transaction, and the money lands on the card as a credit rather than as cash. If your balance is at zero, that credit sits there until you spend it or ask your issuer to move it to a bank account.
Timelines: the casino's own pending period runs from ten minutes to 48 hours depending on the operator, then the network adds one to five business days. There is no way to shorten the second leg, so if speed matters, choose Interac or an e-wallet for withdrawals even when you deposited by card.
Do not use a chargeback to recover gambling losses. It is not a refund mechanism for a bet you regret. Filing one closes the casino account, usually blacklists you across the operator group, and can end with the debt in collections. If you believe a casino has genuinely withheld a legitimate payout, go to the licensing authority named in its footer instead.
Cheaper ways in than a credit card
Every method below avoids the cash-advance classification, and most of them clear more reliably than a credit card at an offshore casino.
- Interac e-Transfer — the Canadian default: your own bank, Canadian dollars, almost never declined.
- iDebit and Instadebit — pay straight from a bank account without exposing a card number; both are widely accepted at CA-facing sites.
- KOHO or another prepaid Mastercard — the credit card experience without the credit or the fee.
- paysafecard — a cash voucher from retail; deposit-only, and a hard cap on the session.
- E-wallets (Skrill, Neteller, Payz, MuchBetter) — instant both ways, though some operators exclude them from the welcome bonus.
- Crypto — the fastest payouts; buying crypto with a credit card, however, is itself usually treated as a cash advance, so the trap follows you.
Is it safe to give a casino your card?
At a licensed operator, yes, within the ordinary limits of card payments. The cashier is PCI-compliant, the number is tokenised by the gateway rather than stored by the casino, and Canadian issuers push almost every gambling transaction through 3-D Secure — the app prompt or one-time code you see at checkout. That step also shifts liability for a fraudulent charge away from you.
- Check the licence in the footer and open the regulator's link before the first deposit.
- Never send card photos through chat; verification documents belong in the casino's own KYC upload.
- Deposit and withdraw in the same name — third-party cards are refused everywhere and can freeze an account.
- Use a card with a low limit, or a prepaid card, so a compromised cashier cannot cost you more than that.
Credit card bonuses: what qualifies and what does not
Card deposits are the safest way to trigger a welcome offer. Operators frequently exclude e-wallets from a first-deposit bonus, and almost never exclude Visa or Mastercard — so if the promotion is the reason you are depositing, a card is the method least likely to disqualify you by accident. The catch sits elsewhere, in the wagering multiplier and the maximum bet permitted while a bonus is live.
- Regulated Ontario offers are the plainest. Wagering of 15× to 25× is normal there, against 35× to 70× at internationally licensed rooms, because Ontario's advertising rules force clearer terms.
- Max-bet rules void more bonuses than anything else. A C$5 to C$8 per-spin ceiling while wagering is standard, and one accidental C$10 spin can forfeit the balance.
- Look for the cash-out cap before the headline number. Winnings from a bonus are commonly capped at three to five times the bonus amount.
- Skip the bonus if you plan to withdraw quickly. A plain card deposit with no attached terms can leave the moment you want it to.
One thing a casino bonus is not: a reason to deposit more than you planned. A 100% match on C$500 does not make a C$500 deposit cheaper — it makes a C$500 deposit look like an opportunity, which is precisely the point of it.
Where card gambling is legal in Canada
Gambling regulation in Canada sits with the provinces, so the answer depends on where you live rather than on the card in your hand. Ontario runs a licensed private market through iGaming Ontario and the AGCO: operators registered there are domestic merchants, and card acceptance rates are noticeably higher because banks recognise the acquirer. Everywhere else, a provincial Crown site — PlayNow, Espacejeux, PlayAlberta, the Atlantic Lottery Corporation — sits alongside internationally licensed casinos that also accept Canadians.
Canadian law is aimed at operators rather than players, no recreational player has been prosecuted for playing at an offshore site, and recreational winnings are not taxable income. The practical difference is recourse: if a regulated Ontario operator withholds a payout you can escalate to the AGCO, while a dispute with an offshore casino goes to its own licensing authority and, at best, to an independent mediator. That gap is worth more than a slightly larger bonus.
Full list of credit card casinos in Canada
| # | Casino | Score | Visa | Mastercard | Amex | Card payout | Min deposit |
|---|---|---|---|---|---|---|---|
| 1 | BetMGM Ontario | 9.8 | Yes | Yes | Yes | No | C$10 |
| 2 | bet365 Casino | 9.7 | Yes | Yes | Yes | Yes | C$10 |
| 3 | NorthStar Bets | 9.5 | Yes | Yes | No | No | C$10 |
| 4 | LeoVegas | 9.4 | Yes | Yes | Yes | Yes | C$10 |
| 5 | Betway | 9.3 | Yes | Yes | Yes | Yes | C$10 |
| 6 | Casino Days | 9.2 | Yes | Yes | No | No | C$10 |
| 7 | Lucky Days | 9.1 | Yes | Yes | No | Yes | C$20 |
| 8 | Rizk | 9.0 | Yes | Yes | No | No | C$10 |
| 9 | Spin Casino | 8.9 | Yes | Yes | Yes | Yes | C$10 |
| 10 | LuckLand | 8.8 | Yes | Yes | No | No | C$10 |
| 11 | 22Bet | 8.7 | Yes | Yes | No | No | C$10 |
| 12 | National Casino | 8.6 | Yes | Yes | No | No | C$30 |
| 13 | Vulkan Vegas | 8.5 | Yes | Yes | No | No | C$20 |
| 14 | Mr Bet | 8.4 | Yes | Yes | No | No | C$20 |
| 15 | FastPay Casino | 8.4 | Yes | Yes | No | Yes | C$20 |
| 16 | BitStarz | 8.3 | Yes | Yes | No | No | C$20 |
| 17 | Cobra Casino | 8.2 | Yes | Yes | No | No | C$20 |
| 18 | PlayZilla | 8.1 | Yes | Yes | No | No | C$20 |
Credit and risk
A credit card is the only casino payment method that lets you lose money you do not have. Set a deposit limit inside the casino before the first bet, keep the card you use on a low limit, and check whether your issuer allows a gambling block — several Canadian banks will apply one to your account on request, and it can be a genuinely useful tool.
Free, confidential help across Canada: ConnexOntario 1-866-531-2600 · Gambling Support BC 1-888-795-6111 · AGLC Alberta 1-866-332-2322 · Aide-jeu Québec 1-800-461-0140. Credit counselling: Credit Counselling Canada.
Credit card casino questions
Do online casinos take credit cards in Canada?
Yes. All eighteen casinos listed here accept Visa and Mastercard from Canadian players, and five also take American Express. Whether the individual charge clears depends on your issuer's policy on gambling merchants, not on the casino.
Is a casino deposit treated as a cash advance?
Frequently, yes. Many Canadian issuers classify gambling charges as cash advances, which adds a fee of about C$3–C$5 and starts interest at 21–23% immediately, with no grace period. Debit, Interac and prepaid cards avoid this entirely.
Which Canadian banks allow online gambling transactions?
Policies vary by bank and by card product, and they change. In our testing RBC, TD and Tangerine cards usually went through — often coded as cash advances — while BMO, CIBC, Scotiabank and Desjardins were mixed. A prepaid Mastercard such as KOHO was the most consistent. Call the number on your card for a definitive answer.
Can I withdraw casino winnings to my credit card?
At six of the casinos listed here. The money arrives as a credit against the card rather than as cash, the casino takes a few hours to two days to approve it, and the network adds one to five business days. Interac or an e-wallet is usually faster.
Which casinos accept Mastercard in Canada?
All eighteen on this page. Mastercard deposits behave much like Visa; the difference shows up on withdrawals, where network rules make card payouts far less common than with Visa.
Can I use a prepaid card such as KOHO at a casino?
Usually yes — a reloadable prepaid Mastercard works at most of the sites above. It caps your spending at whatever is loaded and cannot trigger a cash advance, but it cannot receive a withdrawal, so pair it with Interac for payouts.
What should I do if my card keeps being declined?
Stop retrying — repeated attempts trigger a fraud lock. Try a smaller amount, use a debit or prepaid card, choose a casino that bills in Canadian dollars, and confirm the billing address matches your issuer's records. If it still fails, the block is set at your bank and only your bank can lift it.